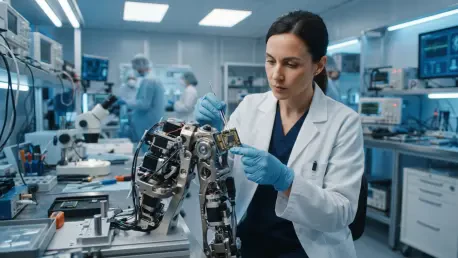
Industry leaders like Micron Technology are positioning humanoid robots as a long-dated growth story that mirrors the evolution of the autonomous vehicle market. This shift signifies a fundamental change in how global semiconductor manufacturers view the robotics sector, moving it from a niche experimental field to a critical pillar of future compute demand. Recent data from Counterpoint Research highlights this trajectory, forecasting a massive twentyfold increase in Dynamic Random-Access Memory demand for humanoid robots by 2030. Specifically, the market is expected to witness a surge from approximately 8,300 terabits in 2026 to a remarkable 172,000 terabits by the end of the decade. This rapid expansion is not merely a result of higher production volumes but also reflects the increasing complexity of robotic systems. As these machines transition toward more sophisticated physical AI models, the average DRAM capacity per unit is projected to grow from 19 gigabytes to nearly 40 gigabytes.
Balancing Long-Term Ambition With Current Production Economics
Elon Musk has emerged as a primary catalyst for the belief that robotics will eventually dominate the entire semiconductor landscape. In late October, he asserted that the memory requirements for mobile robots will eventually surpass all other Earth-based applications combined. His philosophical framework posits that while superintelligence might reside in deep space data centers to maximize thermal efficiency, humanoid robots are fundamentally necessary to interact with and shape physical matter on the planetary surface. This perspective suggests that the transition to a robot-heavy economy will require a massive redistribution of global compute resources. Critics often view such projections as overly optimistic, yet the underlying logic remains consistent with the increasing reliance on localized processing for autonomous systems. If billions of humanoid units are to eventually populate factories and homes, the sheer volume of memory needed to support their real-time sensor fusion would indeed challenge the dominance of existing sectors.
However, a distinct tension exists between visionary long-term rhetoric and the immediate practicalities of mass manufacturing. Despite high-level predictions of infinite demand, current production decisions reflect a cautious approach to component costs and supply chain stability. For instance, recent technical updates confirmed that memory specifications for high-end robotic chips were actually reduced to facilitate higher production volumes for the Optimus platform. This reduction in DRAM per unit—from initial high-performance targets to more sustainable levels—underscores the difficulty of balancing cutting-edge performance with commercial viability. As manufacturers work toward producing thousands of units, the high price of advanced memory modules remains a significant barrier. This dynamic suggests that the path to 2030 will be defined by a series of iterative improvements rather than a single explosive jump. For the industry to reach its projected capacity, it must solve the riddle of making sophisticated robotic hardware affordable for enterprise use.
Measuring the Fiscal Impact on Global Semiconductor Ecosystems
For a major semiconductor player like Micron Technology, the robotics narrative currently serves as a promising prospect rather than a dominant revenue driver. When analyzing the broader financial landscape, it becomes clear that the immediate impact of humanoid robotics on the global memory market is relatively small. Current projections suggest that the total DRAM demand from the robotics sector will account for less than 0.05% of the total global output of nearly 50 exabytes. This statistic highlights the immense scale of the existing digital infrastructure, where data centers and mobile devices continue to consume the vast majority of produced silicon. Investors often react strongly to news involving AI-driven robotics, yet the fiscal health of chipmakers remains tied to traditional high-volume segments for the foreseeable future. While the growth rate is mathematically impressive, the base from which it starts is narrow, meaning that humanoid robots are not yet in a position to influence the cyclical nature of the memory market.
Industry executives maintain that the hardware trajectory for robots will eventually mirror the evolution of the autonomous vehicle market. CEO Sanjay Mehrotra has noted that humanoid robots are likely to adopt memory and storage configurations similar to those found in level-four and level-five autonomous cars. These vehicles frequently carry over 200 gigabytes of memory to support complex navigation and safety protocols, a figure that is significantly higher than the current average for robotic prototypes. If humanoid machines follow this path toward high autonomy, the actual demand for DRAM could far exceed the 39 gigabytes per unit estimated by market researchers for the end of the decade. This potential upside suggests that the semiconductor industry may be underestimating the long-term intensity of robotic compute requirements. As these machines move beyond simple repetitive tasks toward environments requiring complex social interaction, the need for high-bandwidth memory will likely become a non-negotiable requirement for any platform.
Strategic Pathways for Next-Generation Robotics Integration
The technological landscape is currently shifting toward specialized hardware designed to meet the rigorous energy efficiency demands of mobile robotics. Because humanoid robots are battery-powered and must operate for extended periods without recharging, power-efficient memory is becoming a critical competitive advantage. Micron and its competitors, such as SK hynix, are already sampling next-generation low-power double data rate modules to key customers in the robotics space. These components are engineered to deliver high performance while minimizing the thermal footprint, which is essential for maintaining the integrity of the robot’s internal cooling systems. The transition toward LPDDR6 technology represents a pivotal moment in this evolution, as it offers the bandwidth necessary for real-time AI processing without the prohibitive power draw of traditional server-grade memory. As the competition between manufacturers intensifies, the ability to provide customized solutions for physical AI will likely dictate which companies capture the largest share of the market.
The journey toward 2030 required stakeholders to balance technological innovation with the economic realities of global supply chains. Decision-makers identified that moving beyond the prototype phase necessitated a strategic focus on cost-efficient scaling and the development of specialized clean-room capacity. It was determined that the most successful organizations were those that integrated memory planning early in the robot design process, ensuring that hardware limitations did not stifle software evolution. By focusing on low-power solutions and high-bandwidth interfaces, the industry established a foundation for more capable and autonomous humanoid systems. Furthermore, investors recognized that the traditional memory cycle remained a primary risk, prompting a shift toward more resilient procurement strategies. Ultimately, the industry moved to synchronize production timelines with the expected surge in robotic deployment, ensuring that the anticipated DRAM shortage did not impede progress, while establishing a firm ground for physical AI growth.